Fund payroll by credit card. Keep your cash longer.
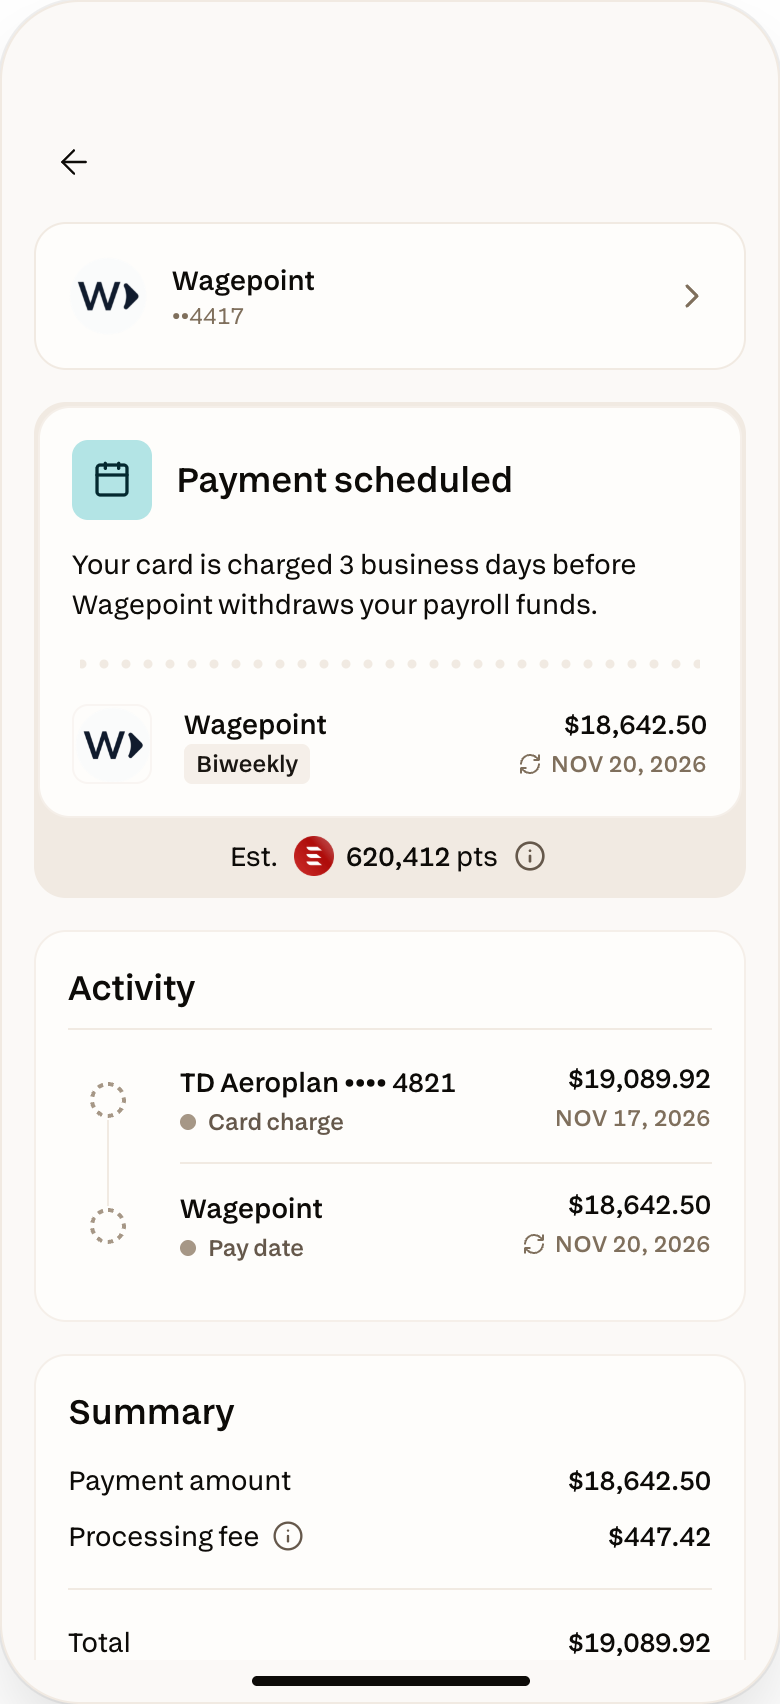
Fund your payroll provider on Visa or Mastercard. Your team gets paid on payday like always. And you keep your payroll provider.
Works with Wagepoint, Dayforce, Payworks, QuickBooks Payroll, Employment Hero and more.
As featured in

What your payroll is worth on a card.
- Each payroll stays in your account about 30 days, until your card bill is due. With payroll every 2 weeks, that’s about two payrolls of cash on hand at any time.
- Each payroll run × 26, on a card that collects 1.25 points per $1. Your card may collect more or less.
Remittances due? Put them on the card too.
Source deductions are a tax, so they go to the CRA at 1.99%. Amex works here too.
How CRA payments workOne payroll run, start to finish.
- Mon, Nov 23Card chargedVisa or Mastercard. Points on the full payroll.
- Thu, Nov 26Provider fundedBy PAD or EFT, same as from your bank.
- Fri, Nov 27PaydayYour team gets paid.
- Mon, Dec 21*Card bill dueThat’s when the cash leaves your account.
Same payroll. Better timing.
Your team gets paid. You earn points on it. You pay your card in full Dec 21.*
*Example dates. Your card bill is due on your card’s statement due date, set by your card issuer, not Chexy.
Payroll fees, upfront.
And you can write it off as a business expense.
- Funding your payroll provider or paying staff directly2.4%
- Over $100K a month on your accountLower rate
- CRA payroll remittances1.99%
CRA remittances take any card, Amex included.
Over $100K a month? We’ll set up your first payment with you.
Payroll questions.
Which payroll providers work?
Businesses on Chexy fund payroll through Wagepoint, Dayforce, Payworks, QuickBooks Payroll, Employment Hero and more. Don’t see yours? Book a call and we’ll check it for you.
Which cards can fund payroll?
Visa or Mastercard, business or personal. You can also fund payroll from your bank. Source deductions to the CRA take any card, Amex included.
Does my payroll provider need to do anything?
If your provider pulls funds by pre-authorized debit, give it your Chexy PAD details once. If you send funds by EFT, add its banking details as a payee.
When should I schedule the funding?
For the date your provider needs the money, not payday. Your card is charged 3 business days before that date, so add it at least 4 business days ahead.
Can I pay staff or contractors directly?
Yes, by e-Transfer or EFT. Chexy sends the payment. Withholding and remittances stay with you or your provider.
What if a card charge doesn’t go through?
Adding the payment early leaves time to approve the charge, switch cards, or split the amount across Visa or Mastercard cards before payday.
Is this taking on debt?
Not if you pay your card in full when it’s due. It’s the payroll you already run, on a card you already have, paid off on your normal statement. If you carry a balance, your card’s interest applies, so we don’t recommend it.
Is the fee tax deductible?
For most businesses, yes. Chexy’s fee is a business expense, like a bank or card fee. Your accountant has the final say.